

rapid! Pay
by Green Dot
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
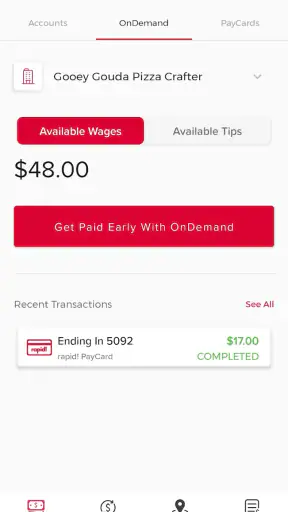
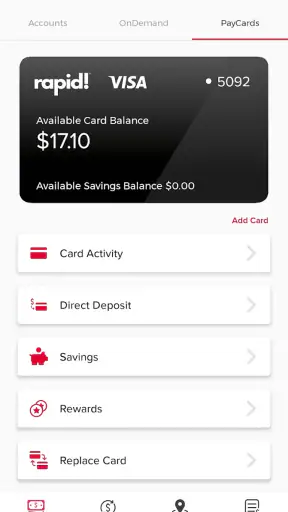
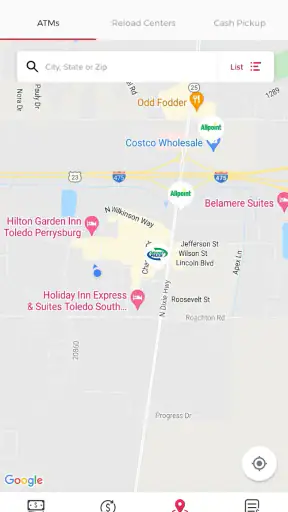
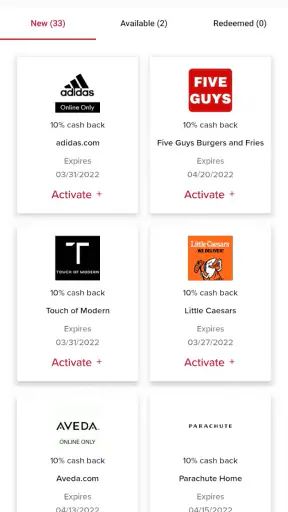
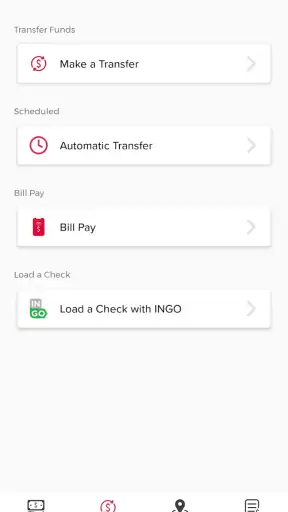
 Analysis by Getfullapps
I approached rapid! Pay as a practical finance app rather than as another general-purpose banking tool. Its role is closely tied to the rapid! card experience, so the right question is not simply whether it looks polished, but whether it fits the way you already receive, spend, and monitor money through that card. After using it, my view is straightforward: it can be a useful companion for cardholders who want mobile access in one place, while people looking for a complete replacement for a traditional bank may find its narrower purpose limiting.
The app is free to download and is made by Green Dot. It is rated for Everyone, works on Android devices running version 7.0 or later, and has reached over a million installs. Its current release is version 1.0.116. Those details make it accessible to a wide range of Android users, although compatibility alone does not decide whether it is the right financial tool for you.
How to Decide Whether rapid! Pay Fits Your Routine
My first decision criterion is simple: do you already use a rapid! card, or are you planning to register one? The app is built around that relationship. If your everyday money activity is connected to rapid!, the mobile interface has a clear purpose. If you want a broad budgeting platform, investment service, loan manager, or multi-bank dashboard, you should compare it with apps designed specifically for those jobs before switching.
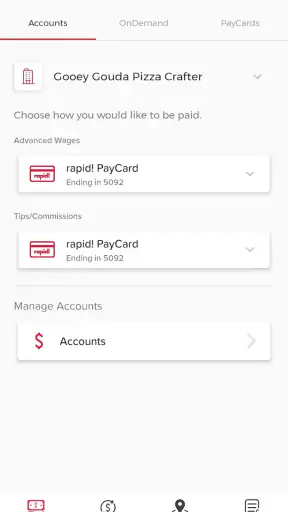
The second criterion is how often you need to check your money. A card companion is most valuable when it reduces small points of friction: opening the app to review activity, checking whether a purchase has appeared, or keeping an eye on available funds without handling paperwork. I found that this kind of access matters most for people who make frequent card purchases and prefer a phone over a browser.
There is also a registration question. The store summary presents rapid! Pay as a way to register new users quickly, so the onboarding path is an important part of its appeal. In practice, I would prepare the information associated with your rapid! card before beginning. Having your card details and personal information ready makes the first session less frustrating than starting casually and then searching for documents halfway through.
The app makes the most sense when your card is already central to your daily spending. That sounds obvious, but it prevents a common mistake: downloading a card-specific app while expecting the wider tools of a full bank account. I would decide what I need to accomplish on my phone first, then judge rapid! Pay against that list.
What the mobile experience is good at
rapid! Pay’s strongest quality is focus. Instead of trying to become a financial super-app, it gives rapid! cardholders a dedicated place to interact with their card. That focused design can be easier to understand than a crowded banking application filled with mortgages, savings products, investment charts, and promotional sections that are irrelevant to a cardholder.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also like the practical value of having card-related information available while away from a computer. Imagine being at a supermarket and wanting to check your available funds before completing a larger shop. Opening a phone app is more convenient than waiting until you get home or trying to remember the last balance you saw. The same applies when reviewing a purchase after leaving a restaurant or checking activity during a busy week.
Another useful workflow is making the app part of a short weekly money check. I would open it at the same time each week, review recent card activity, and compare what I see with receipts or personal notes. That habit is more valuable than repeatedly opening the app without a purpose. It can help spot an unfamiliar transaction sooner and gives you a clearer sense of how quickly your card balance changes.
The app’s popularity also gives it some reassurance for prospective users. It holds an average rating of 4.3 from around 78 thousand ratings, with roughly 14 thousand written reviews. I do not treat ratings as proof that every person will have a smooth experience, but they suggest that rapid! Pay is established enough to have been used and assessed by a substantial audience.
Where the focused design becomes a limitation
The same focus that makes rapid! Pay approachable may feel restrictive if you manage several financial products. A typical bank app may bring checking, savings, transfers, statements, and other services together. A budgeting app may categorize spending across different accounts. rapid! Pay should not be chosen on the assumption that it will replace every one of those tools.
I would also avoid treating a card companion as a complete financial planning system. If your main goal is building a detailed monthly budget, tracking household spending across multiple people, or comparing long-term savings targets, a dedicated budgeting application may be a better fit. You can still use rapid! Pay for card activity, but you may need another tool for the broader picture.
There is a mental trade-off here. A specialized app can reduce clutter, but it can also create one more place to check. If you already use a bank app, a payroll portal, and a budgeting service, adding rapid! Pay only helps if its card access is valuable enough to justify that extra step. For me, the deciding factor would be whether I regularly need rapid!-specific information while away from the other services.
Everyday situations where it earns its place
Consider a worker who receives money through a rapid! card and uses that card for commuting, groceries, and small household purchases. Their priority is not investment analysis. They want a quick way to stay aware of card activity and avoid relying on memory. For that person, rapid! Pay has a sensible role: it puts the relevant card relationship on the phone they already carry.
A second use case is someone who is new to the rapid! card and wants a clear starting point. The registration emphasis can make the app feel more direct than beginning with a general financial platform. I would still read each screen carefully during setup, especially where personal details or account credentials are involved, rather than rushing through simply because the process is described as rapid.
A third scenario involves someone who wants a simple separation between card spending and other finances. Keeping card activity in its own app can make it easier to see what is happening on that card without mixing it with unrelated accounts. The downside is that you must remember to combine the figures yourself when calculating your full monthly spending.
Small habits that make the app more useful
My first practical tip is to use rapid! Pay as a verification checkpoint, not just a balance viewer. After an important purchase, check that the activity appears as expected when it is convenient. This creates a routine for noticing unfamiliar activity early, rather than discovering a problem much later among a long list of transactions.
My second tip is to pair the app with a simple spending note if you need stronger budgeting. rapid! Pay can be the source for card activity, while a note or separate budget records categories such as food, transport, and recurring expenses. This avoids expecting the card app to perform a job it was not designed to be your only solution for.
My third tip is to make registration a deliberate session. Do not begin while distracted in a queue or during a rushed commute. A careful setup reduces the chance of entering information incorrectly and gives you time to understand what the app is asking for. The quick-registration message is useful, but speed should not come at the expense of accuracy.
Finally, keep the app updated when your device supports the current release. rapid! Pay was released on October 30, 2020, and its present version is 1.0.116. I would check that the version shown on my device is current before judging performance, because an older installation can behave differently from the maintained release.
How it compares with the usual alternatives
Compared with a traditional bank app, rapid! Pay is more specialized. A bank app may be the better choice if you want several account types, broader money movement, or one place for an established banking relationship. rapid! Pay is more appealing when the rapid! card itself is the center of your activity and you do not want unrelated banking features in the way.
Compared with a general budgeting app, the difference is even clearer. Budgeting tools are normally designed to combine information, set spending plans, and show patterns across categories or accounts. rapid! Pay is better approached as a direct card companion. If your decision depends on detailed household budgeting, I would use a budgeting tool alongside it or choose a service that already brings all your accounts together.
Compared with managing the card through a mobile browser, a dedicated app can be more convenient for repeated checks. The advantage is not necessarily a bigger feature list; it is having a purpose-built entry point on your phone. The browser route may suit someone who rarely checks the card and does not want another installed app, while rapid! Pay suits someone who expects regular mobile access.
Compared with a prepaid-card app from another provider, the important comparison is not just appearance. Look at the card relationship, registration process, and the financial tasks you actually need. Since rapid! Pay is developed by Green Dot for the rapid! experience, it is most logical for people whose card already belongs in that ecosystem. Switching to another provider only for a different interface may create unnecessary work if your current card meets your needs.
The real cost of changing your setup
Switching to rapid! Pay is relatively easy to imagine if you are already a rapid! cardholder: install the free app, complete registration, and make it part of your checking routine. The less obvious cost is behavioral. You may need to change where you look for card information, update saved habits, and decide whether your existing bank or budgeting app remains part of the process.
For someone moving away from a full banking application, the cost can be higher because a specialized card app may not cover every task previously handled in one place. You could end up checking two applications instead of one. That is not automatically bad; separating card activity can improve clarity. But I would switch only if rapid! Pay solves a specific access problem rather than simply adding another icon to the home screen.
There is also a learning curve during the first few sessions. Even a straightforward finance app deserves careful attention because mistakes in registration or account selection are more consequential than mistakes in a casual entertainment app. I would spend time confirming that the displayed card information matches what I expect and would keep a separate record of important financial details while becoming familiar with the workflow.
The app is free, which removes a subscription decision, but free does not mean frictionless. The value comes from convenience and fit, not from collecting another application. If you rarely use the rapid! card, the benefit may be too small to matter. If you depend on it every day, the dedicated access can justify the change quickly.
Who should use it and who should look elsewhere
I would recommend rapid! Pay to an existing rapid! cardholder who wants a straightforward mobile connection to that card. It is especially suitable for people who check spending on the go, prefer phone-based access, and do not need a single application to manage every financial product they own.
I would also consider it for a new rapid! user who wants to begin with the card’s own mobile experience rather than assemble a complicated system immediately. Starting with one focused app can make daily monitoring less intimidating, provided the user understands that wider budgeting or banking needs may call for another service later.
I would be more cautious for someone whose main requirement is multi-account budgeting, investment management, detailed financial reporting, or a broad bank replacement. In those cases, a full-service bank app or dedicated budgeting platform is likely to be a better primary tool. rapid! Pay could still have a supporting role, but I would not make it the center of that setup.
People who dislike maintaining separate apps should also think carefully. The focused design is a benefit only when the information it provides is worth the extra destination. If your current financial app already gives you all the card visibility you need, switching may not improve your routine enough to notice.
My recommendation after weighing the trade-offs
rapid! Pay is a sensible choice when convenience around a rapid! card matters more than having an all-in-one financial dashboard. I like its clear purpose, free access, broad Android compatibility, and emphasis on getting cardholders into the mobile experience without unnecessary complexity. Its 4.3 average and over a million installs also indicate that it has found a substantial audience.
My recommendation is therefore conditional rather than universal. If rapid! is already part of your everyday money routine, I would install rapid! Pay and use it as the dedicated checkpoint for card activity. Build a weekly review habit, use it alongside a simple budget if necessary, and treat registration as a careful process rather than a race.
If you are searching for a complete replacement for your bank, or you need deep planning across several accounts, I would choose a broader alternative first. rapid! Pay is not at its best when forced to be something larger than a rapid! card companion. It is at its best when you want that specific relationship to be easier to manage from your phone.
In short, I see it as a practical, focused finance app rather than a universal money manager. For the right cardholder, that focus is exactly the reason to use it. For everyone else, the better decision may be to keep a broader financial tool at the center and use a specialized card app only when it genuinely saves time.
Pros
- Fast QR and contactless payments at participating merchants.
- Supports rewards and cashback opportunities on eligible purchases.
- Simple interface makes everyday transactions easy to manage.
- Payment history helps users track spending in one place.
- Available for quick transfers between supported users or accounts.
Cons
- Requires participating merchants and supported regions to work fully.
- Some features may depend on bank, card, or account compatibility.
- Internet or mobile connectivity may be needed for transactions.
- Rewards and cashback terms can vary and may include restrictions.
- Users should review privacy settings before linking financial information.
FAQs for rapid! Pay
What is rapid! Pay and what can I use it for?
rapid! Pay is a mobile payment and money-management app designed for eligible rapid! Pay cardholders. After signing in, users can typically review their available balance, check recent transactions, manage card-related settings, and access account information from a smartphone. The exact features available may depend on the card program, employer, account type, and region, so it is worth confirming eligibility before downloading.
Is rapid! Pay available for both Android and iPhone?
The rapid! Pay app may be available through the official Google Play Store and Apple App Store, depending on your country and the specific rapid! Pay service offered there. Before installing, check the developer name, app logo, ratings, supported operating-system version, and recent update date. Avoid downloading APK files or unofficial copies, since financial apps should only be installed from trusted, official sources.
How do I sign in to rapid! Pay for the first time?
To use rapid! Pay, you generally need an eligible rapid! Pay account or card and the login details associated with it. New users may need to register, verify their identity, confirm a phone number or email address, and create a secure password or PIN. If you cannot access your account, use the in-app recovery options or contact official customer support rather than sharing credentials with anyone.
Is rapid! Pay safe for managing payment-card information?
rapid! Pay is intended for handling sensitive payment and account information, so users should keep the app updated and enable a device passcode, fingerprint, or face authentication whenever supported. Never disclose your password, one-time verification code, or card details through unsolicited messages. Review notifications and transactions regularly, and contact the official support team immediately if you notice an unfamiliar login, transfer, or card activity.
Are there fees or requirements for using rapid! Pay?
Downloading rapid! Pay is commonly free, but using the related card or account may involve fees, limits, eligibility rules, or transaction conditions established by the card issuer or program provider. Mobile-data charges from your carrier can also apply. Review the current terms, fee schedule, privacy policy, and account agreement before relying on the app for payments, transfers, balance access, or other financial services.

rapid! Pay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via rapidappsupport@rapidpaycard.com, visit https://rapidwages.com, or review their https://www.go2bank.com/agreements/technology-privacy-statement.










